

CCC Intelligent Solutions Holdings Inc. (Nasdaq: CCC) said Q3 2025 revenue rose 12% to $267 million, from $238.5 million in the same period last year. This matches the software seller’s Q2 revenue growth, also at 12% year over year. Gross profit rose 5% to $193 million, while gross profit margin was 72%, down from 77% YOY.
Quarterly adjusted gross profit was just shy of $200 million, up 7.5% from $186 million. CCC adjusted gross profit margin was 75% in Q3 2025 and 78% in Q3 2024. CCC has previously said it aims for an 80% adjusted gross profit margin.
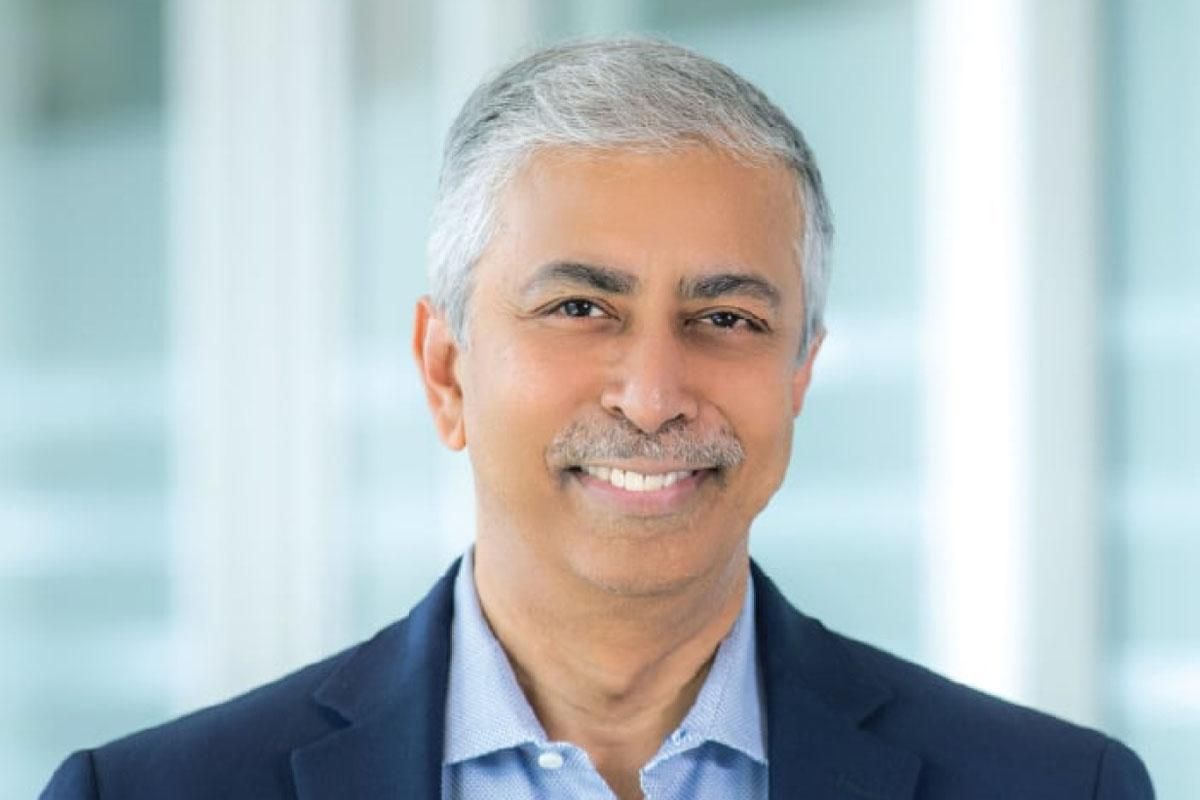
“CCC delivered strong third quarter results,” Chairman and CEO Githesh Ramamurthy said in an earnings press release. “Our financial performance reflects continued momentum across our platform.”
“Lower adjusted gross profit margin is mostly driven by higher depreciation from newly launched solutions and software enhancements,” said Brian Herb, executive vice president, CFO and chief administrative officer, on an earnings call.
CCC reported results Oct. 31.
Other Metrics, Outlook
GAAP operating income was $30 million in Q3, up 5%. GAAP net loss was $2 million, a $6 million reversal from $4.1 million net profit in Q3 20224. Adjusted EBITDA was $110.1 million, up 8% from $101.6 million last year.
Herb said on the call CCC ended the quarter with $97 million in cash and equivalents, and $993 million in debt, for 2.1x EBITDA leverage ratio.
“We continue to show improving trends in free cash flow generation,” Herb said. “Free cash flow in Q3 was strong at $79 million. That compares to $49 million in the prior year period.” He said this was due to “strong collections and favorable timing on working capital.”
Trailing 12 months free cash flow was $255 million, up 28%.
Looking ahead, Herb said CCC expects annual revenue of $1.051 billion to $1.056 billion — 12% year-over-year growth, matching each of the last two quarters.
Insurance, AI, Ticker
Herb noted continuing decline in industry claim volumes, which fell 6% in the third quarter, after an 8% drop in Q2 and a 9% downward spike in Q1.
Collision repair companies have noted the decline in recent earning calls. Justin Jude, CEO of LKQ Corp., also reporting results Oct. 31, told analysts “repairable claims continue to experience downward pressure, though the rate of decline has moderated to approximately 6%.”
Ramamurthy on CCC’s earnings call said the company continues to sign new clients in both insurance and repair, while others expand and upgrade their buying.
“Liberty Mutual, the sixth largest auto insurer in the United States by 2024 direct premium written, has signed with CCC and is actively transitioning a substantial portion of their casualty business to our platform,” he said, and “a top 20 insurer signed on for Intelligent Reinspection, our workflow AI solution, demonstrating the growing demand for intelligent automation across the claim life cycle.”
CCC Intelligent Solutions Holdings Inc. on Oct. 31 dropped its old ticker symbol, CCCS, and began trading under a new one, CCC. Shares are still traded on Nasdaq.










Paul Hughes