
With body shops and consumers increasingly viewing the right to appraisal as a key element in getting fully compensated for collision repair damage or total losses, a recent panel discussion focused on getting that right — and using it.
During this summer’s Collision Industry Conference (CIC), just weeks before right to appraisal legislation was signed into law by the Illinois governor, Beth Seberger was asked what it took to get the legislation passed by lawmakers.
Lobbyists and borrowed bill language moved Illinois forward
“A lot of money, and a lot of hard work,” Seberger, president of the Alliance of Automotive Service Providers of Illinois (AASP-Illinois), which pushed for the legislation, said. “I joke when I say a lot of money, but at the end of the day, you really do need lobbyists. We did hire lobbyists last year, and they helped us form the relationships that we didn’t have with key members within our state: our department of insurance, our secretary of state. I now have the ability to email, call, reach out when we need something. We haven’t had that in many years.”
She said the association first thought rulemaking rather than legislation was the route to take, and spent a year working with the state’s department of insurance. After that, she said, they realized legislation was the way to go. She said the language for the bill was drawn from similar legislation in other states, including Texas (where it was enacted in 2025) and Rhode Island.
“We kind of took a little bit from here, took a little bit from there, wrote our bill and introduced it to [a state legislator] who wanted to run with it,” Seberger said. “We got lucky in forming relationships with our state reps and our state senators in getting the ball rolling. It wasn’t until May that we finally started getting responses from the insurance lobbyists and the other interested stakeholders, and started going back and forth with the language.”
Illinois law narrowed during negotiations
She said several aspects of the original bill were eliminated during the process. The original version called for the insurer to cover all costs of the appraisal process if the final appraisal award is “10 percent or more favorable to the policyholder…compared to the insurer’s last written offer prior to appraisal.” But as finalized, each side bears their own costs for the process.
Also stricken from the bill was a provision calling for the establishment of an eight-member “Automotive Appraisal Standards Advisory Board” to provide guidance on rule-making, enforcement priorities, and best practices. And under the new law, only first-party insureds have the right to appraisal, not third-party claimants, for example.
“We’re working on the third-party side still, but we knew that that wasn’t going to be something that we would probably see,” Seberger said. “But our main focus was the right-to-appraisal language being in every policy for first-party.”
Helping customers use the appraisal process
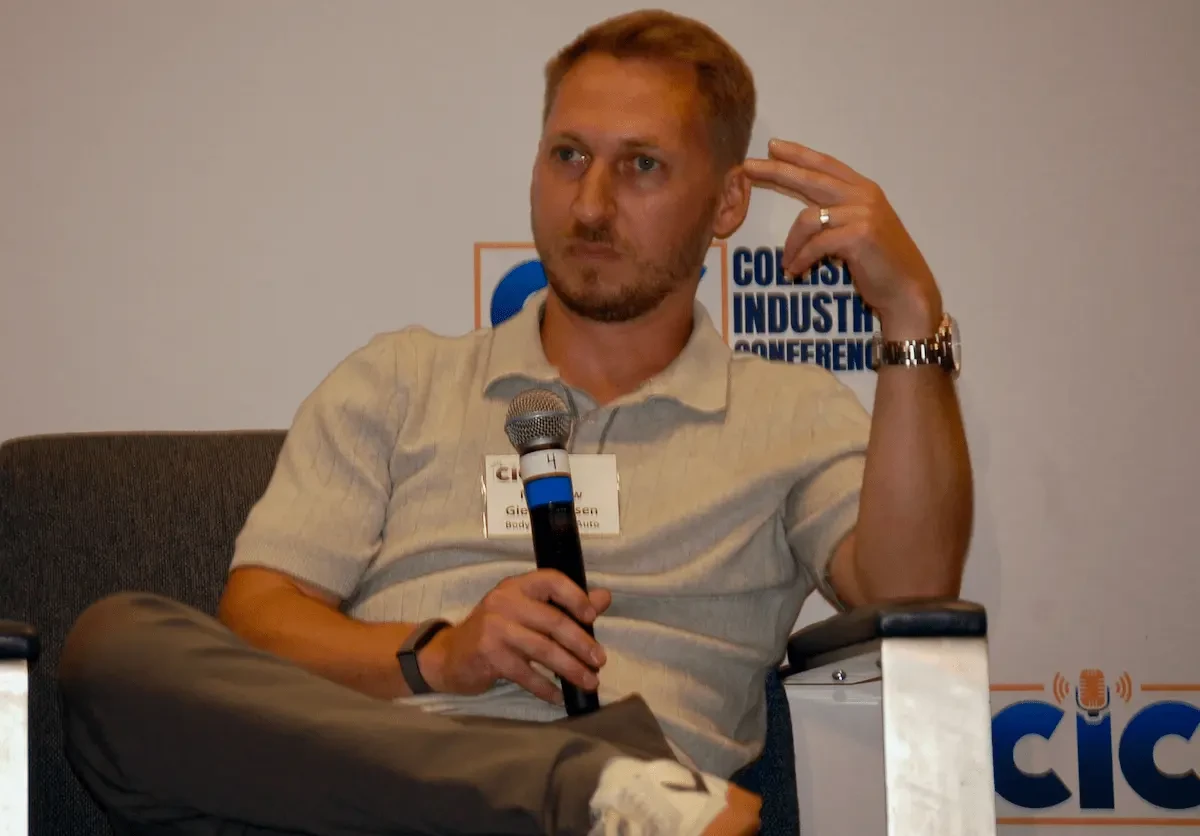
During the panel discussion, representatives from several shops discussed helping customers use the appraisal process. Matt Giebelhausen of Body Builders Automotive in the Chicago area said his company’s initial consultation with customers includes discussion of all the steps that could be involved in assisting them with their claim.
“If their insurer has the right-to-appraisal, then we kind of walk them through that process, telling them it’s not a definite, it’s not an end-all and be-all, but it is another tool in your belt that you as a consumer can use to get reimbursed and fully indemnified versus paying out-of-pocket,” Giebelhausen said.
Justin Lewis of Accurate Auto Body in Redmond, Washington, helped get right-to-appraisal legislation enacted in his state in 2025.
“I find at our shop, it almost relaxes a customer to understand that if there is a short-pay, there is an opportunity,” Lewis said. “It’s not a guarantee, but there’s an opportunity to get reimbursed for the expense of the repair. At the end of the day, as a service provider, our job is just to provide a safe and proper repair of that vehicle. A lot of consumers don’t deal often with automotive. There’s almost like a block that goes up when you start talking cars with a lot of people. But the appraisal clause, if the shop understands it and can help the consumer understand it, it helps build confidence with that consumer. It helps them sit back and relax a little bit.”
“I think you’ve got to remember that most consumers are used to paying the deductible, getting your car fixed, going down the road and never thinking about it again,” Giebelhausen said. “In reality, with safety inspections and OEM parts and requirements, and calibrations, that’s just not the case anymore. All these things start to add up, and most insurance carriers have strict guidelines that they have to follow. Which we understand, but at the end of the day, as a shop, we’re responsible for fixing the car safely, properly. We try to minimize the out-of-pocket expense for a customer. But I always tell them, it’s never zero, especially if you want OEM parts,if you want a safe and proper repair, if you want the correct people doing calibrations to make sure that your vehicle is going to act the way that it should. Unfortunately, that all comes with a cost, and one way to minimize out-of-pocket expense can be the right-to-appraisal.”
Consultant says too few total loss claimants use appraisal
Two other panelists at CIC came at the appraisal topic from a perspective outside of a shop. Ken Klein of Consumers’ Auto Detective, a collision consulting firm in Elgin, Illinois, said he believes too few consumers are using the appraisal clause, particularly for first-party total loss claims.
“Of the people that contact me, I would say at least three-quarters of them need to go [through] the appraisal clause,” Klein said. “They’re mostly all being shorted, though the amount that they’re being shorted isn’t [always] worth what the cost of the appraisal would be. But sometimes the [insurer is] taking the [total loss-related] fees that the shops are charging out of the settlement offers. That can all be eradicated through the appraisal clause.”
Sean Preston, a Massachusetts-based attorney, said the appraisal clause can reduce the problem of finding an attorney to help a consumer with a short-pay that may be only a few hundred or a few thousand dollars.
“Even if you find an attorney willing to take it, is the attorney going to understand the industry, understand the repairs, understand property damage claims,” Preston said. “And so, what we look for is an alternative dispute resolution: arbitration, mediation. Those are common ones. But the right to appraisal is another one.”
Attorney urges shops to prepare for a slow process
Preston cautions that shops should be realistic when assisting a consumer with using the appraisal clause.
“When you look at the process, it is not necessarily quick,” Preston said. “The other side may attempt to slow down the process at literally every stage. They can draw it out so long and it can be really messy. I know that the shops here want the best for your customers. It’s not just your job to do a safe and proper repair. It’s your legal responsibility to do a safe and proper repair. Every single one of those steps, you need to take the time to understand them, to be able to explain them, because you can get held up at any single one of those.”

John Yoswick