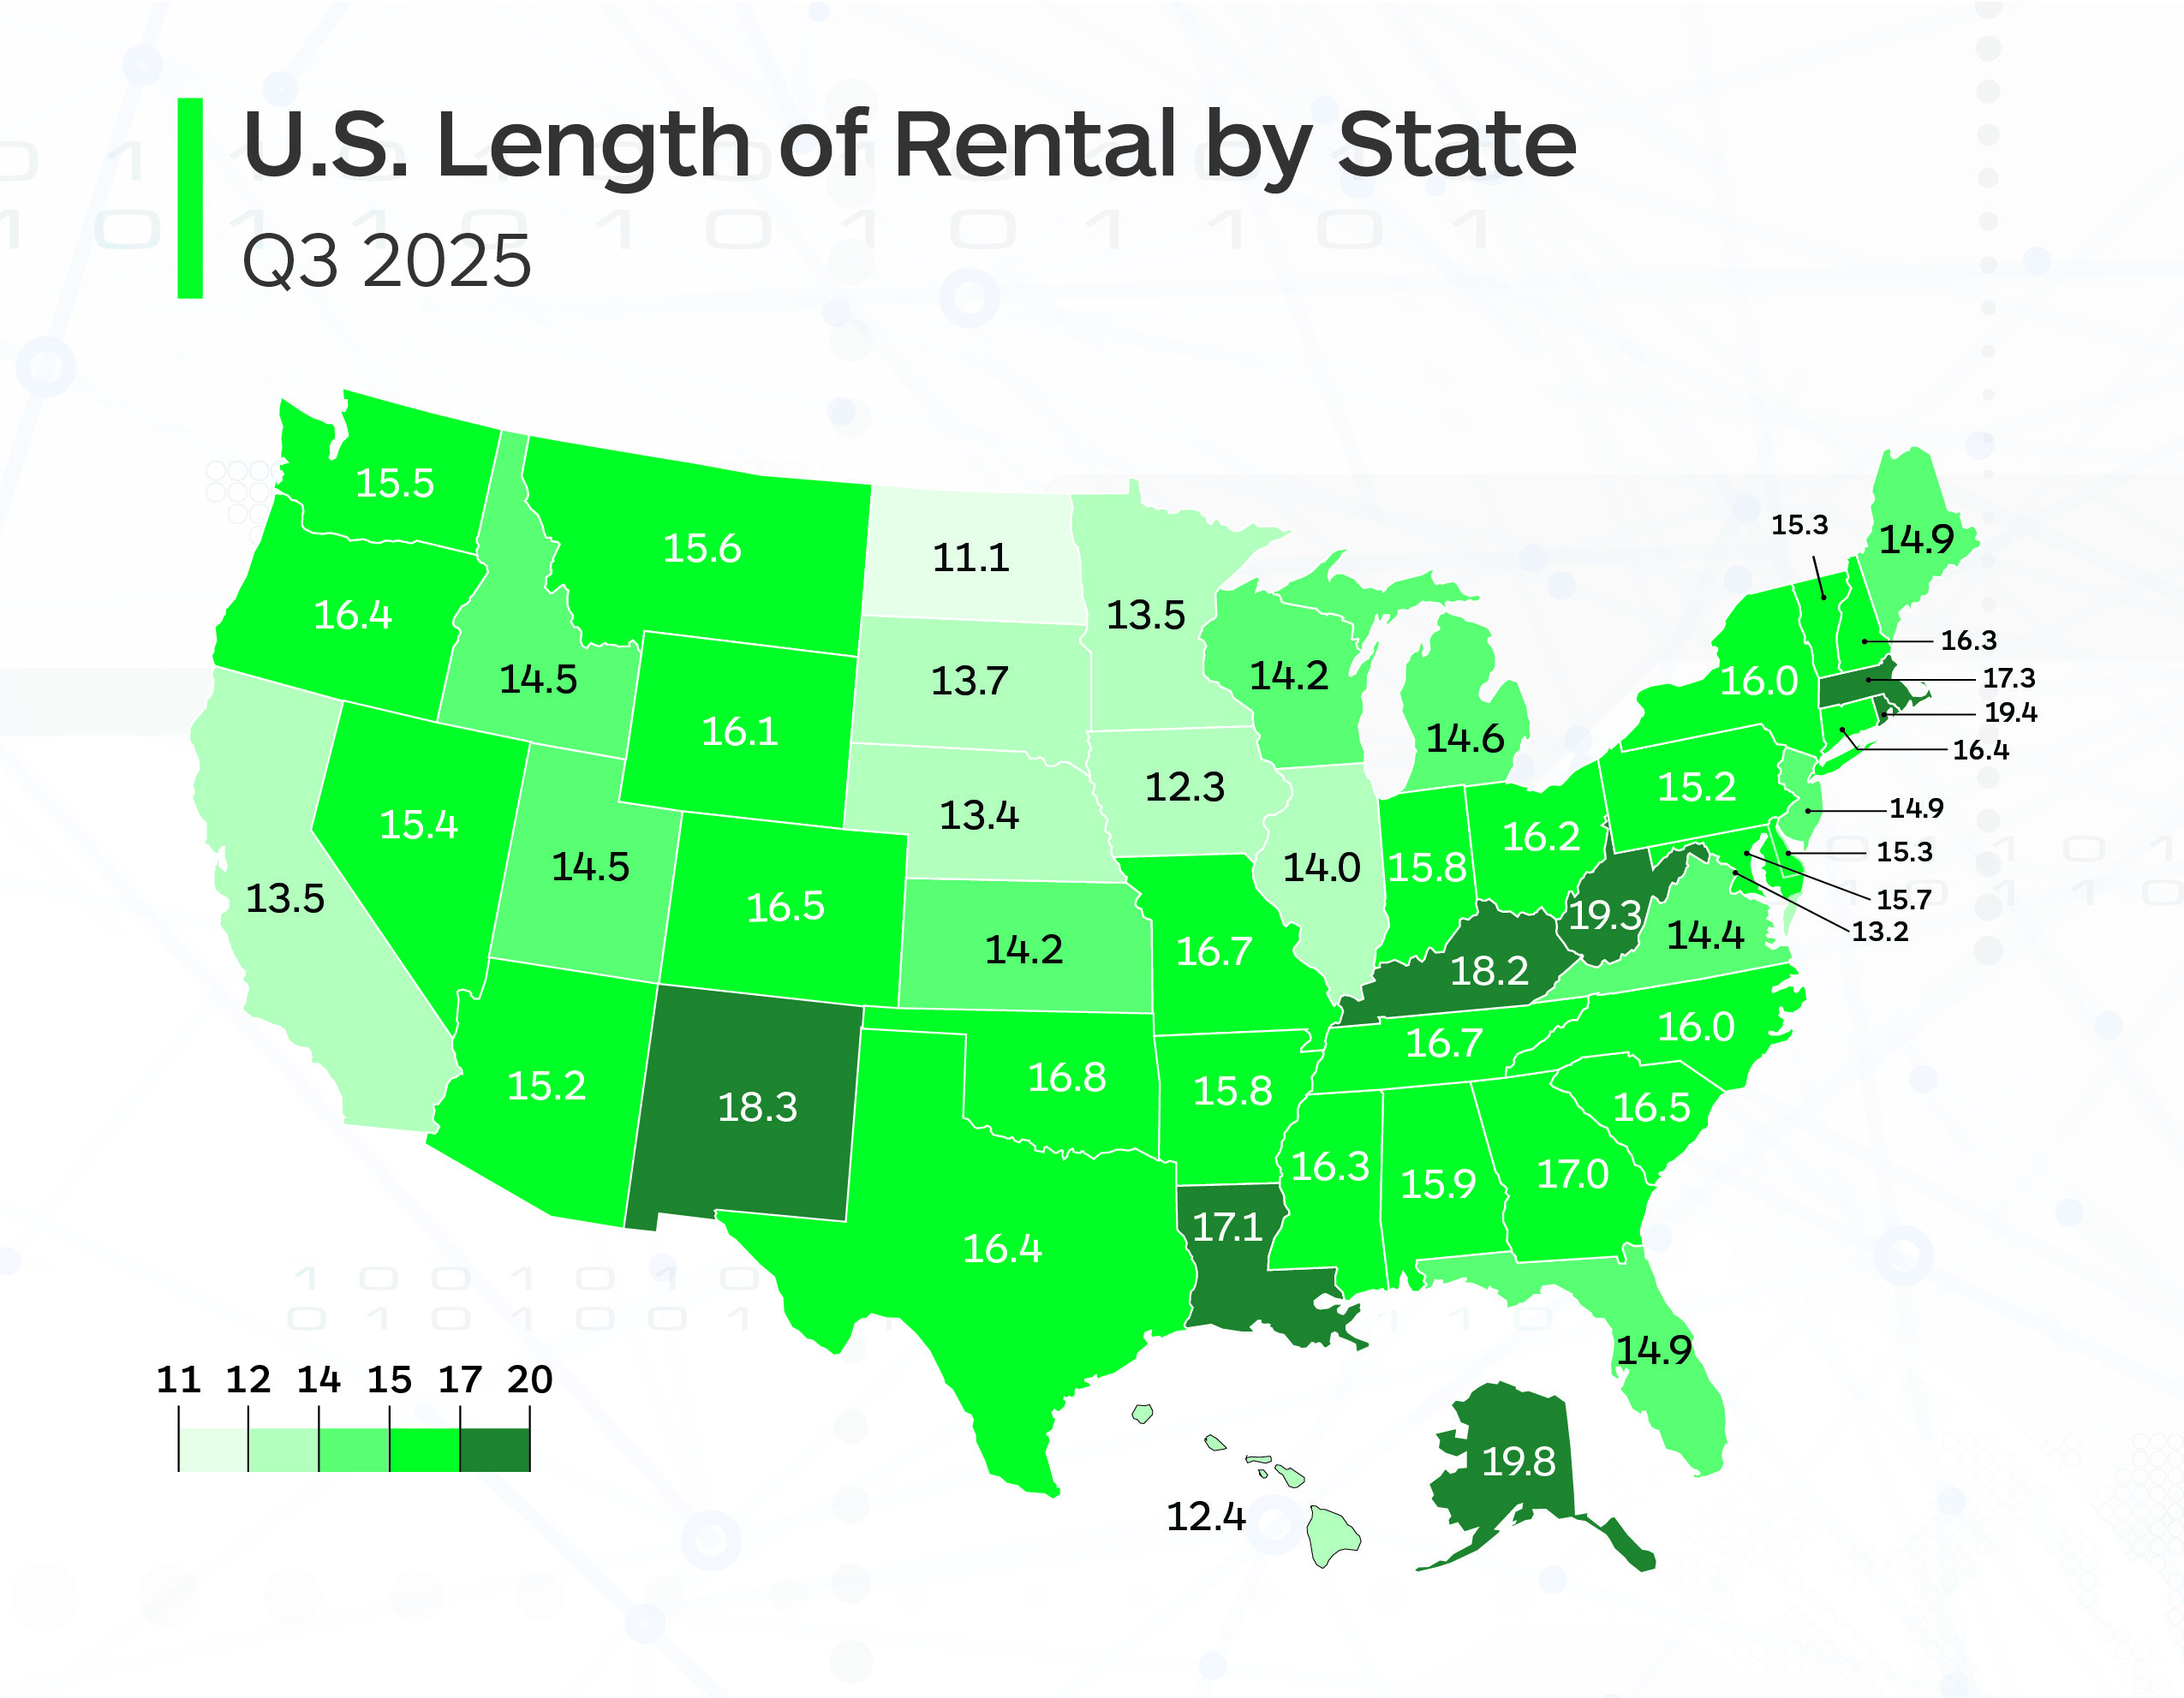
While length of rental (LOR) for collision-related rentals in Q3 2025 continued its decrease from post-pandemic highs, ongoing market and economic conditions could impact future results.
The overall LOR for the quarter was 15.5 days, a 0.9-day decrease from Q3 2024, similar to the decline seen in both Q1 2025 and Q2 2025, according to new data from Enterprise.
The post-COVID effects of vehicle production and supply chain issues had an outsized impact on LOR in 2022 and 2023. When comparing the most recent quarter to the same in 2021, overall LOR is currently 0.3 days higher. However, Q3 2021 showed a nearly three-day increase over Q3 2020, when LOR was 12.3 days.
Alaska recorded the highest overall LOR at 19.8 days, followed by Rhode Island at 19.4 days and West Virginia at 19.3 days.
North Dakota had the lowest overall LOR at 11.1 days, with Iowa (12.3 days) and Hawaii (12.4 days) next lowest.
Washington, D.C., had the highest increase, with LOR up 0.6 days compared to Q3 2024. Kentucky (+0.3 days), Ohio (+0.1 days) and West Virginia (+0.1 days) were the only other states with increases, while Pennsylvania and Vermont were flat.
Colorado saw the largest overall decrease in LOR with its 16.5 days representing a full three-day decrease. Texas was down 2.3 days, and Nebraska was down 2.1 days.
Greg Horn, PartsTrader’s chief industry relations officer, compared parts data to LOR.
“Using the median plus two standard deviations to reduce outliers, Q3 2025 saw a significant reduction in overall median delivery days, measured at 6.8 days, compared with 9.5 days for Q3 2024,” Horn said.
“All part types had reduced delivery days, but we noted the biggest decreases were for new OEM and OEM price-matched parts,” he added. “For specific states, PartsTrader data aligned with Colorado at 3.3 fewer days, California with 2.9 fewer days, and both Nebraska and Texas with 2.4 fewer median delivery days.”
John Yoswick, editor of the weekly CRASH Network newsletter and an Autobody News contributor, offered insights from data from the “Who Pays for What?” survey of more than 600 shops conducted by Collision Advice and CRASH Network.
“We see a number of factors contributing to the modest decline in LOR,” Yoswick said.
Scheduling backlogs at shops around the U.S. this summer was essentially unchanged from the prior quarter, increasing by less than half a day.
“Not since the second quarter of 2021 had the national average backlog of work at shops been less than two weeks, but it’s been at that level (1.8 weeks in July) for two consecutive quarters this year,” Yoswick said.
Nearly one in four shops — about 24% — said they could schedule work immediately, up more than three percentage points from the prior quarter.
“In the nearly nine years since the surveys began tracking backlogs, the percentage of shops with no backlog had never exceeded 20%, outside of the pandemic year of 2020, until the two most recent quarters,” Yoswick said.
Ryan Mandell, VP of strategy and market intelligence for Mitchell International, remarked on impacts that alternative parts usage (APU) might be having on results.
“Alternate parts utilization is at an all-time high with 40.6% of replacement parts being classified as aftermarket, recycled or remanufactured,” Mandell said. “In Q3 2024, that number was 38.3%. Even with an expected decline due to supplement development, we can still expect the final number for Q3 2025 to end above what we observed during the same time period the year prior.
“Generally speaking, alternative parts are less prone to delays and back orders than OEM parts, resulting in faster throughput and keys-to-keys cycle times,” Mandell added.
He said the percentage of parts repaired also rose to 17%, up from 15.4% in Q3 2024.
Drivable
In Q3 2025, drivable LOR was 14.4 days, a 0.7-day decline from Q3 2024.
Alaska and Rhode Island had the joint-highest drivable LOR at 18.2 days. North Dakota had the lowest drivable LOR at 9.8 days, with Hawaii next lowest at 11.1 days, followed by Iowa at 11.2 days.
Kentucky had the highest drivable LOR increase, up 0.6 days. The District of Columbia (+0.5 days) and Ohio (+0.3 days) were next highest. Colorado also saw a 3.0-day decrease with drivable claims, with Nebraska and Texas both down 2.1 days compared to Q3 2024.
Non-Drivable
Non-drivable LOR was 21.2 days in Q3 2025, down 1.1 days from Q3 2024. Alaska was highest at 29.5 days, closely followed by West Virginia at 29.4 days, with third-highest New Mexico at 25.6 days. Iowa had the lowest non-drivable LOR with 17.8 days, followed by Nebraska at 18.8 days, and California and Minnesota at 18.9 days each.
The District of Columbia had the highest non- drivable increase, with its 19.2 days representing a 1.1-day increase. West Virginia was the only other state with an increase, up 0.6 days, while North Dakota and Hawaii were flat. Colorado also had the highest decrease in Q3 2025, with its 22.3 days down 4.1 days from Q3 2024. Vermont was down 3.2 days, while Nebraska and Arkansas both declined by 3.1 days.
“The length of time shops are waiting for re-inspections or supplement approval continues to be higher than pre-pandemic,” Yoswick noted. “In the CRASH Network survey results, shops said they are waiting 4.6 days on average for an insurer to complete an in-shop inspection. That is down from the peak of more than five days in 2023, but still well above the 2.9- day average wait time reported in 2018.”
Yoswick said wait times for remote or “virtual” inspections also declined, averaging 3.8 days: “Shorter than the 4.6-day peak in 2023, but still a day-and-a-half longer than shops reported back in 2018.”
Total Loss
LOR for rentals associated with total loss claims was 13.9 days in Q3 2025.
West Virginia had the highest total loss LOR at 19.0 days, followed by Kentucky (17.3 days) and Alaska (16.4 days). North Dakota had the lowest total loss LOR with 11.2 days, closely followed by Wyoming (11.4 days) and Iowa (11.9 days).
Mississippi and Alaska had the highest increases, with total loss LOR up 0.5 days each in Q3 2025. Kentucky (+0.1 days) was the only other state with an increase, while West Virginia’s results were flat. Wyoming had the largest total loss decrease, with LOR down 6.9 days. Next lowest were New Mexico (-3.5 days) and Vermont (-3.4 days).
“Total loss frequency declined from 20.9% in Q3 2024 to 20.3% in Q3 2025,” Mandell said. “The primary reason for this decline was the slight increase experienced in total loss market values (1.78% in Q3 2025) as a result of consumer-driven demand for vehicle purchases, both new and used, in order to take advantage of pricing before any potential tariff impacts felt by OEMs were passed along to consumers.”