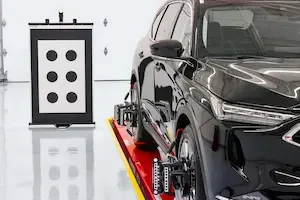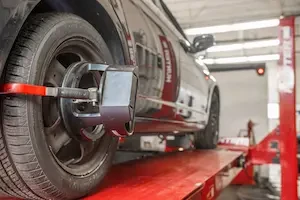

A quarter of collision repair shops have invested in ADAS calibration equipment but still aren't capturing the work consistently enough to make it pay off, according to a new framework from Revv that quantifies where shops stand on calibration readiness and what it takes to move forward.
The ADAS Calibration Maturity Curve, published by Revv in March, maps shops across five stages based on scores in five categories: calibration capability, documentation and compliance, tooling and equipment, workflow integration, and revenue capture.
The model draws on a 300-shop benchmark survey that Revv conducted in late 2025, which found that while 86% of shops handle at least some calibrations in-house, only about one in five have fully optimized the process. The average shop in that study reported roughly $21,500 per month in ADAS revenue at net margins around 9%, after a median equipment investment of about $55,000.
"The industry has crossed the awareness chasm," said Adi Bathla, co-founder and CEO of Revv. "Everybody knows that this is here, this needs to be done, it is now a core part of the repair workflow. But now the question is, how do we go about it?"
Where the industry sits
The survey data shows a wide spread across the five stages. Roughly 42% of shops are in the bottom two tiers — either fully outsourcing calibrations or operating with limited, reactive capability. One in four sits at Stage 2 (Emerging), where they've purchased equipment and started bringing some work in-house but lack consistent processes.
Another 20% are at Stage 3 (Established), running competent in-house operations with growing revenue. The remaining 38% have reached Advanced or Leader status, with optimized or market-leading operations.
That 42% figure is notable given that 65% of repairs now require at least one ADAS recalibration, according to Revv's data.
The equipment trap
The one in four shops at Stage 2 represent what Bathla described as the framework's most important finding: shops that have committed capital but aren't seeing returns.
"You have made the investment and you're already doing the work," Bathla said. "But you still have a massive leaky bucket."
At Stage 2, shops are identifying calibration needs reactively, often based on visible damage to sensors rather than systematic research tied to the vehicle's specific ADAS configuration. Capture rates sit around 20%, meaning the vast majority of billable calibration work is walking out the door.
Bathla said the natural assumption is that profitability will come once the equipment is in place, but the data tells a different story.
"Most shops, rightfully so, think that my readiness to absorb the ADAS work is actually about equipment," he said. "But what the data is telling us from the maturity curve is that the bottleneck is actually the process."
What changes between stages
The transition from Stage 2 to Stage 3 is where Revv's data shows the sharpest improvement in financial performance. Capture rates jump from roughly 20% to 50%–80% as shops implement repeatable workflows for identifying, performing, and documenting calibrations. By Stage 4, capture rates reach 80%–95%, and by Stage 5, they exceed 95%.
Bathla framed each stage in terms of what layer the shop has built. At Stage 2, a shop has equipment. At Stage 3, it has added a process layer — logging calibrations, building documentation habits, and creating repeatability. At Stage 4, it has a systems layer, where every stakeholder in the shop knows when to identify calibration needs and where to interject in the repair cycle. At Stage 5, those systems extend beyond the shop's own rooftop to serve external customers.
"The shops winning at this ADAS game — they're not the ones that have the most expensive or the best tools," Bathla said. "They're the ones who have actually built repeatable processes and systems to perform this work and wrap their operations around it."
With the ADAS portion of a typical repair running between $500 and $1,500, the revenue difference between a 20% capture rate and a 60%–80% capture rate across dozens of vehicles a month adds up quickly.
Documentation as the tipping point
Bathla said documentation is where process improvements translate most directly into financial results. He outlined three reasons: it determines whether shops get paid by insurers, it reduces liability exposure as ADAS-related litigation increases, and it positions shops to comply with state-level legislation that increasingly requires proof of calibration work.
"This is a services industry with razor-thin margins, and the last thing you want is doing the work that you don't get paid for," Bathla said.
The shift tends to happen between Stage 3 and Stage 4, when documentation moves from a manual, inconsistent effort to an automated part of the workflow. Rather than relying on individual technicians to remember what needs to be recorded, Stage 4 shops have built systems where documentation happens as part of the repair process itself.
"You don't have to think about it because that's not where your revenue is," Bathla said. "You want to focus on the car and the customer and everything else is happening automatically."
A realistic path forward
Bathla said independent shops don't need to reach Stage 5 to benefit from the framework. Moving one or two stages in 2026 is enough to meaningfully close the gap between equipment investment and operational return.
"We're still at a good stage where if you take a few steps into the maturity curve, you are still well positioned to not let the industry and all these external variables move so far away from where your shop is today," he said.
He compared it to building a muscle. "Once you're at the next stage, you realize the revenue, you realize that you're protected, and that pushes you to go further," Bathla said. "This is the biggest thing that has happened to the industry in the past 25 years."