

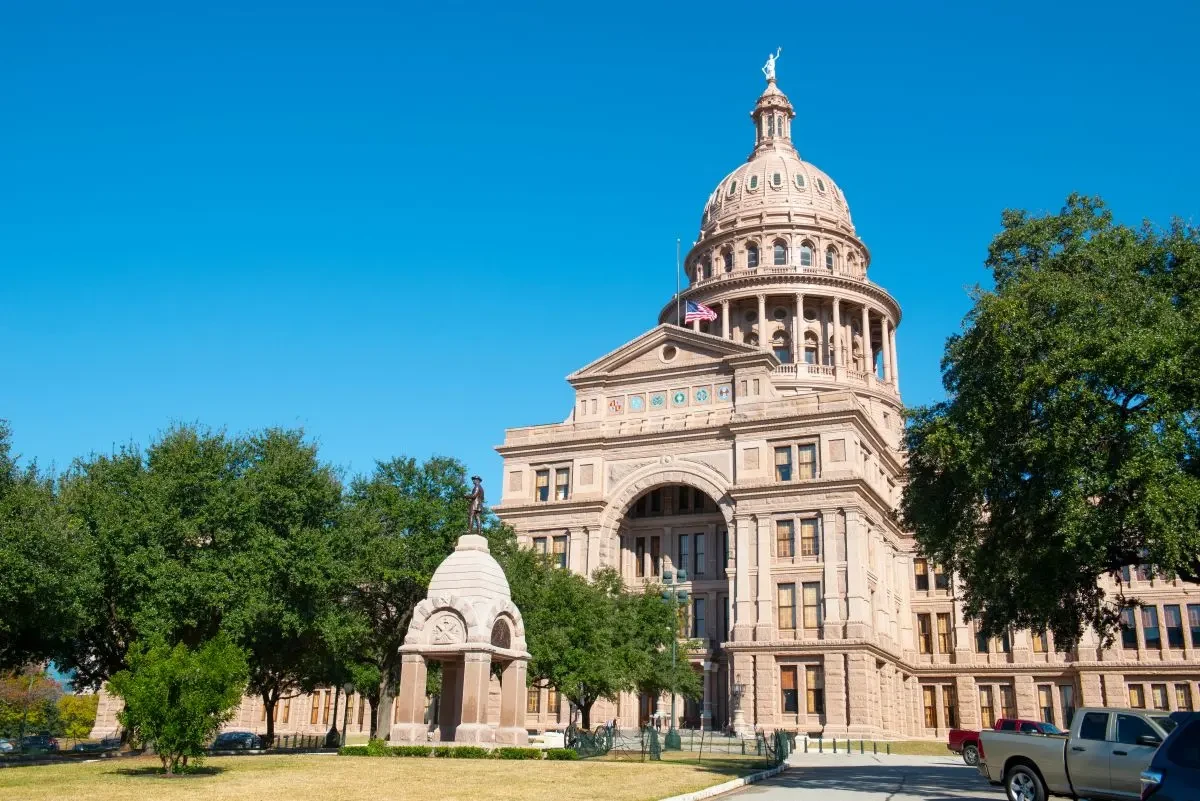
Texas collision repair shops may soon see a shift in how insurance disputes are handled, as the Texas Department of Insurance (TDI) rolls out proposed rules tied to Senate Bill 458 (SB 458).
The rules, outlined in new appraisal requirements under Chapter 1813, aim to standardize the appraisal process across personal auto policies and ensure consumers are aware of their rights when claim disputes arise.
For shops accustomed to drawn-out negotiations and stalled repairs, the changes could introduce a more structured, potentially faster path to resolution.
A More Structured Process
At the center of the proposal is a requirement that all applicable policies include an appraisal provision, giving both insurers and policyholders a formal process to resolve disputes over the amount of loss.
But the biggest shift may be the addition of clear timelines.
Under the proposed rules, policyholders will have a defined window (typically 120 days for auto claims) to demand appraisal after a claim decision is made. Once invoked, both parties must follow a set schedule for selecting appraisers, choosing an umpire and reaching a resolution.
“The most important thing is that it’s mandatory for all Texas policies, and that it has time triggers,” said Robert McDorman, founder of Auto Claim Specialists. “Once you invoke it, there are timelines for when things have to happen.”
For shops, that structure could mean fewer vehicles sitting idle while insurers and repairers go back and forth.
Awareness Could Be a Game-Changer
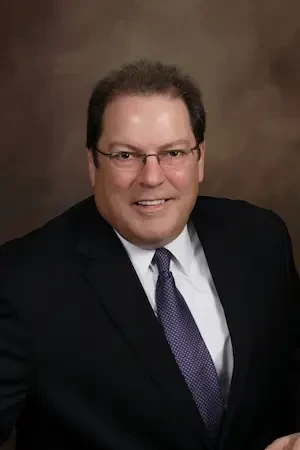 Robert McDorman, founder of Auto Claim Specialists, believes the new Texas appraisal rules will increase consumer awareness and reduce prolonged claim disputes between insurers and repair shops. Another key provision requires insurers to notify customers of their right to appraisal at the same time they accept or deny a claim. The notice must be written clearly and designed to stand out, ensuring policyholders actually see it.
That matters because appraisal has historically been underused.
TDI data cited in the proposal indicates only a small percentage of claims currently go through appraisal, in part because policyholders simply don’t know it’s an option.
“With this notice requirement, every person who has a claim is going to be notified,” McDorman said. “It’s an education process. Folks just weren’t aware they had this right.”
For collision repairers, increased awareness could change conversations at the front counter. Instead of explaining appraisal as a niche or unfamiliar option, shops may soon be reinforcing something customers have already been told by their insurer.
Real-World Impact in the Shop
For shop owners, the stakes are high. Underpaid or disputed claims are not the exception; they’re the norm.
“It’s a very big issue — almost 100 percent of every job we work on,” said Steven Stringer of Reno Paint and Body in Paris, TX. “It’s a major battle.”
Stringer described a common scenario: insurers steering customers toward lower-cost repairs while questioning higher estimates that follow OEM procedures.
“Our estimate is higher because we’re doing what it takes to return the vehicle safely,” he said.
That disconnect can slow down repairs and create friction with customers, especially when insurers position shop estimates as excessive.
The new appraisal rules may help bridge that gap, at least in theory.
“I think it will help,” Stringer said. “At least with the insurer having to inform customers, it won’t seem like something we’re making up.”
Faster Resolutions or New Friction?
One of the biggest questions is whether the rules will actually speed up the repair process.
McDorman believes they will change how disputes are handled by encouraging earlier use of appraisal.
“Once there becomes a dispute … the insured should invoke the right to appraisal,” he said. “This will stop the nonsense of a car sitting there for 60 or 90 days while the shop and carrier try to come to terms.”
By triggering a formal timeline, appraisal could reduce the prolonged negotiations that often leave vehicles in limbo.
But shop owners are cautiously optimistic.
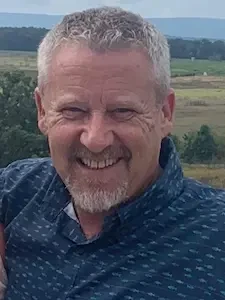 Steven Stringer said the new appraisal notice requirements could help customers better understand their rights during claim disputes.“We have our first client with State Farm to invoke their right to appraisal (RTA) since the law took place,” said Stringer. “We have had hundreds of clients over the years who used the RTA process to resolve their loss dispute with their carrier. Always in the insured customers’ favor.”
Some carriers may take time to adapt, especially those that previously limited or removed appraisal provisions from their policies.
In those cases, disputes often escalated to litigation, which is a costly and time-consuming process.
“We have quite a few customers in litigation right now,” Stringer said. “That can take around 14 months.”
Appraisal, by comparison, is designed to be a faster and more affordable alternative.
A Shift Toward Consumer Protection
At its core, the new rule framework aims to strengthen consumer protections.
The appraisal process binds the amount of loss, meaning it can provide a definitive resolution without going to court — unless there is fraud or a significant error.
McDorman sees the changes as a major step forward.
“This is a huge victory for the insured citizens of Texas,” he said. “It’s 100 percent consumer-focused.”
For collision repairers, that shift could translate into more support when advocating for proper repairs.
What Shops Should Do Now
While the rules are not set to take effect until September 2026, shops have an opportunity to prepare. Understanding the appraisal process and how to guide customers through it may become an essential part of operations.
Just as important will be recognizing when to escalate a dispute.
“If there’s a gap between what the shop says is a safe repair and what the carrier will pay, that’s subject to appraisal,” McDorman said.
For an industry long challenged by underpaid claims and delayed approvals, the new rules may not eliminate friction, but they could introduce a clearer path forward.
And for shops on the front lines, that clarity may be just as valuable as speed.










Leona Scott