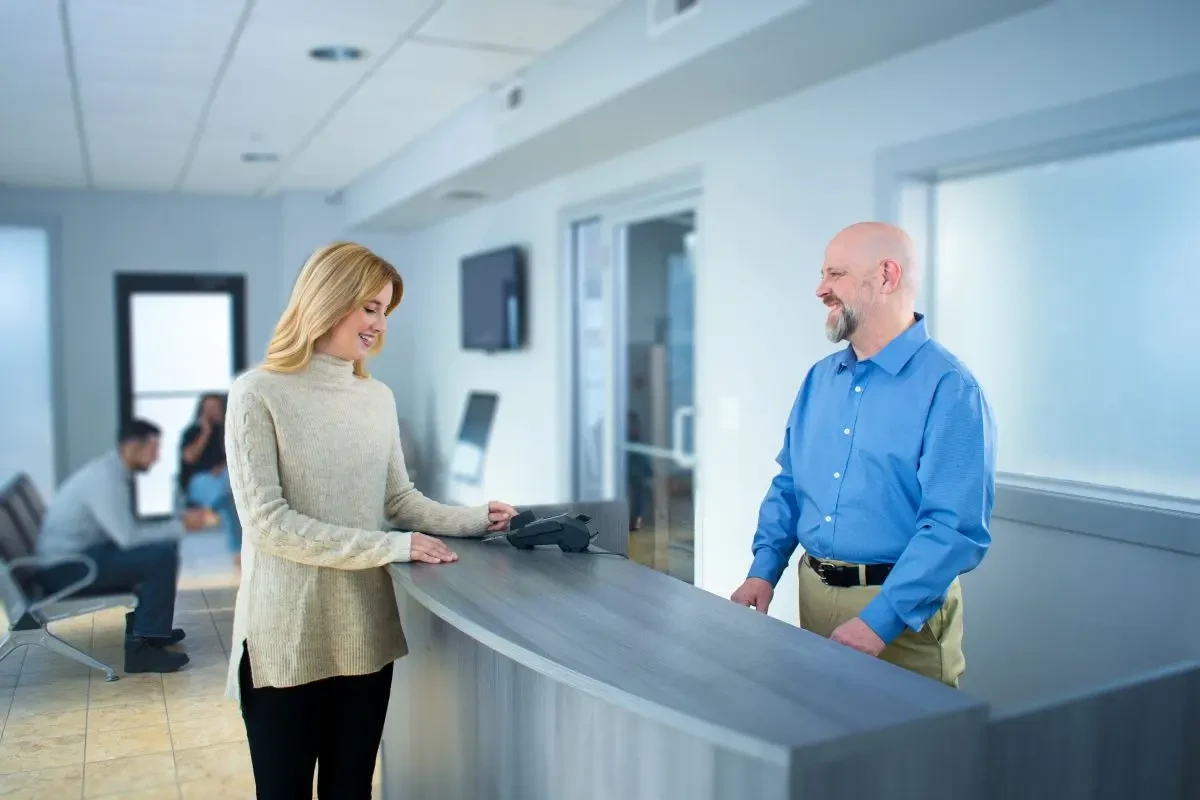
A customer comes into your shop after an accident. The damage is worse than they expected, but they're relieved to have found a shop they trust, and the conversation is going well. Your estimator walks them through the plan, the timeline, the parts. Then you get to the part insurance won't cover, and what they owe out of pocket, and something in the room shifts.
That's usually when the questions start. Can it wait a few weeks? Do I really need to fix that part now? What if we just handle the visible damage for now? When you know the repair is sound and the price is fair, those questions can feel like a customer second-guessing your shop. Most of the time, they're not.
The obstacle in that moment often has nothing to do with your repair plan or your process. It comes down to whether the customer can cover the bill. Here are three things you can put in place to keep the bill from becoming the barrier.
Your Customer Is More Stressed Than They're Letting On
Start by recognizing that today's customer is carrying more financial pressure than you might realize, and that the squeeze has tightened in just the last few years. Higher deductibles, higher vehicle payments, higher insurance premiums, and higher everyday living costs have all landed on the same household budget at the same time.
The deductible piece alone has shifted a lot of the repair bill onto your customer's shoulders. Deductibles of $1,000 or more now make up 28.1% of repairable collision claims, up from 19.3% in early 2021. The share of the bill the customer is responsible for keeps climbing, and for a growing number of people, it's climbing past what they can comfortably cover. The cushion to absorb it is thin, too. In its most recent household survey, the Federal Reserve found that 39% of adults said the largest emergency expense they could cover from savings was under $1,000.
Put those two numbers together and that pause at the counter starts to make sense.
Now the tricky part. Most customers will never say any of this out loud. Financial stress doesn't wear a name tag. It shows up as a delay, as a request to fix only what's absolutely necessary, as a promise to call back that never comes. Read those reactions as doubt about your work and you'll miss what's really going on. Most people want the repair. They're just trying to figure out how to afford it, and once you see that distinction, you're in a position to help.
KEEP IN MIND: THE SIGNALS TO LISTEN FOR
Financial hesitation rarely sounds like a money problem. It sounds like:
- "I need to think about it."
- "Let me call you back."
- "I might have to wait on that."
- "Can we just do the visible damage for now?"
When you hear these, treat them as a cue to talk options, not as a lost sale.
The Job Goes Beyond Writing the Estimate
Think about everything your shop has already done to make repairs easier on your customers. Online scheduling. Text updates. Photo estimating. After-hours drop-off. You didn't add those because customers walked in asking for a specific piece of technology. You added them because customers wanted the process to be easier, and meeting that expectation won you the work.
Payment is the next piece of friction sitting right in that same path. Consumer financing, or any flexible way to pay, belongs in the same category as online scheduling and text updates. It's one more way to give customers options and take an obstacle out of the way.
Part of removing that friction is talking about cost early instead of letting it ambush the conversation at the end. When you bring up the customer's financial responsibility up front, and take a minute to explain why a modern repair costs what it does, the number lands differently. Your customers don't always know that a bumper is full of sensors now, or that hidden structural damage is common and genuinely dangerous to leave alone. A quick, plain explanation of what they're paying for, and what they're risking if the car isn't fixed right, turns the price from a shock into a decision.
The payoff shows up on both sides of the counter. Your customer gets to make the repair decision based on what's safest for their vehicle, rather than only what's in the checking account this week. And your shop holds onto the full, safe repair instead of watching it get whittled down to the parts someone can pay for that day.
Have a Plan Before the Customer Needs One
The third piece ties the first two together, and it doesn't hinge on picking one specific financing product. It's about having a plan, so nobody on your team is ever caught flat-footed.
Eventually every shop meets the customer who truly wants to fix their vehicle and just needs another way to get there. When that happens, the last thing you want is a service advisor with nothing to offer but an apology. Whether your answer is financing, an in-house payment arrangement, or another approach that fits your business, the important thing is having something ready before the customer is standing at your counter.
A plan is only as good as the process behind it. That means handling the money conversation the same way every time, even on the busy days when it's tempting to rush past it. It means bringing cost up early, as a normal part of the walkthrough, so it never has to surface as an objection at the end. And it means following up on the estimates that didn't convert, staying with them until you get a clear yes or a clear no, because a customer who left to "think about the money" is often a customer you can still help.
Just as important, get your team comfortable introducing those options with empathy instead of pressure, so a stressed customer feels like you're on their side. Handle it that way and your shop becomes the place that helped them solve a problem, the kind of experience that brings customers back.
KEEP IN MIND: BUILD THE HABIT INTO THE PROCESS
A plan works when it's consistent. Three ways to make it stick:
- Bring up cost and payment options early, as a normal part of the estimate walkthrough, not as a response to an objection.
- Handle it the same way on busy days as slow ones. No shortcuts when the shop is full.
- Follow up on every unconverted estimate until you get a clear yes or a clear no.
Not Every Payment Option Is Worth Offering
Say you're sold on having a plan. The next question is what to put in front of your customers, and here it pays to be choosy.
Be clear-eyed about this. Some pay-over-time products have earned real scrutiny for predatory lending practices, and you don't want your shop's name anywhere near one of them. The point was never to help a customer take on debt they shouldn't carry. The point is to clear an obstacle that has nothing to do with whether they want their car fixed. Offer something you'd feel good signing up for yourself.
What separates a real capture tool from simply having financing available comes down to a handful of questions. Run any option you're considering against them before you commit.
KEEP IN MIND: FIVE QUESTIONS TO ASK BEFORE YOU COMMIT
- Can an estimator or CSR use it right at the counter, in the moment the conversation matters most, so it works as part of the sale instead of a form somebody digs up later?
- Is it transparent and easy to use from start to finish, for you and for the customer?
- Does it approve customers at a high enough rate that offering it builds confidence instead of stacking another rejection on someone already stressed?
- Are the terms genuinely fair, with true 0% interest options, no late fees, no penalties, no hidden costs, and no hard credit check?
- Does your shop get paid up front at the time of repair, with no repayment risk, so cash flow stays predictable while billing and support are handled directly with the customer?
The Bill, Not the Repair, Is Often the Hurdle
Here's something worth trying this week. Spend some time up front and watch your customer interactions, listening less for the repair decisions and more for the hesitation. Those phrases that come up when a number lands wrong tell you a lot.
The instinct is to hear them as a verdict on your shop or your estimate. More often, they're the sound of a customer quietly trying to find a way to make the repair work. If you already offer financing or flexible payment options, make sure your team is comfortable and confident bringing them up at exactly that moment. If you don't offer anything yet, now's the time to go find the right fit.
The mission of your shop has always been bigger than fixing vehicles. It's getting people safely back on the road, and sometimes the hardest part of that is the bill, not the repair. A shop with a real answer ready for the bill fixes more cars, and sends more customers home safe.
To learn more about how CCC's Consumer Financing solution, powered by Sunbit, can help your shop capture more repairs with over 90% approval and no cost to add it to your CCC ONE subscription, visit cccis.com/consumer-financing.