

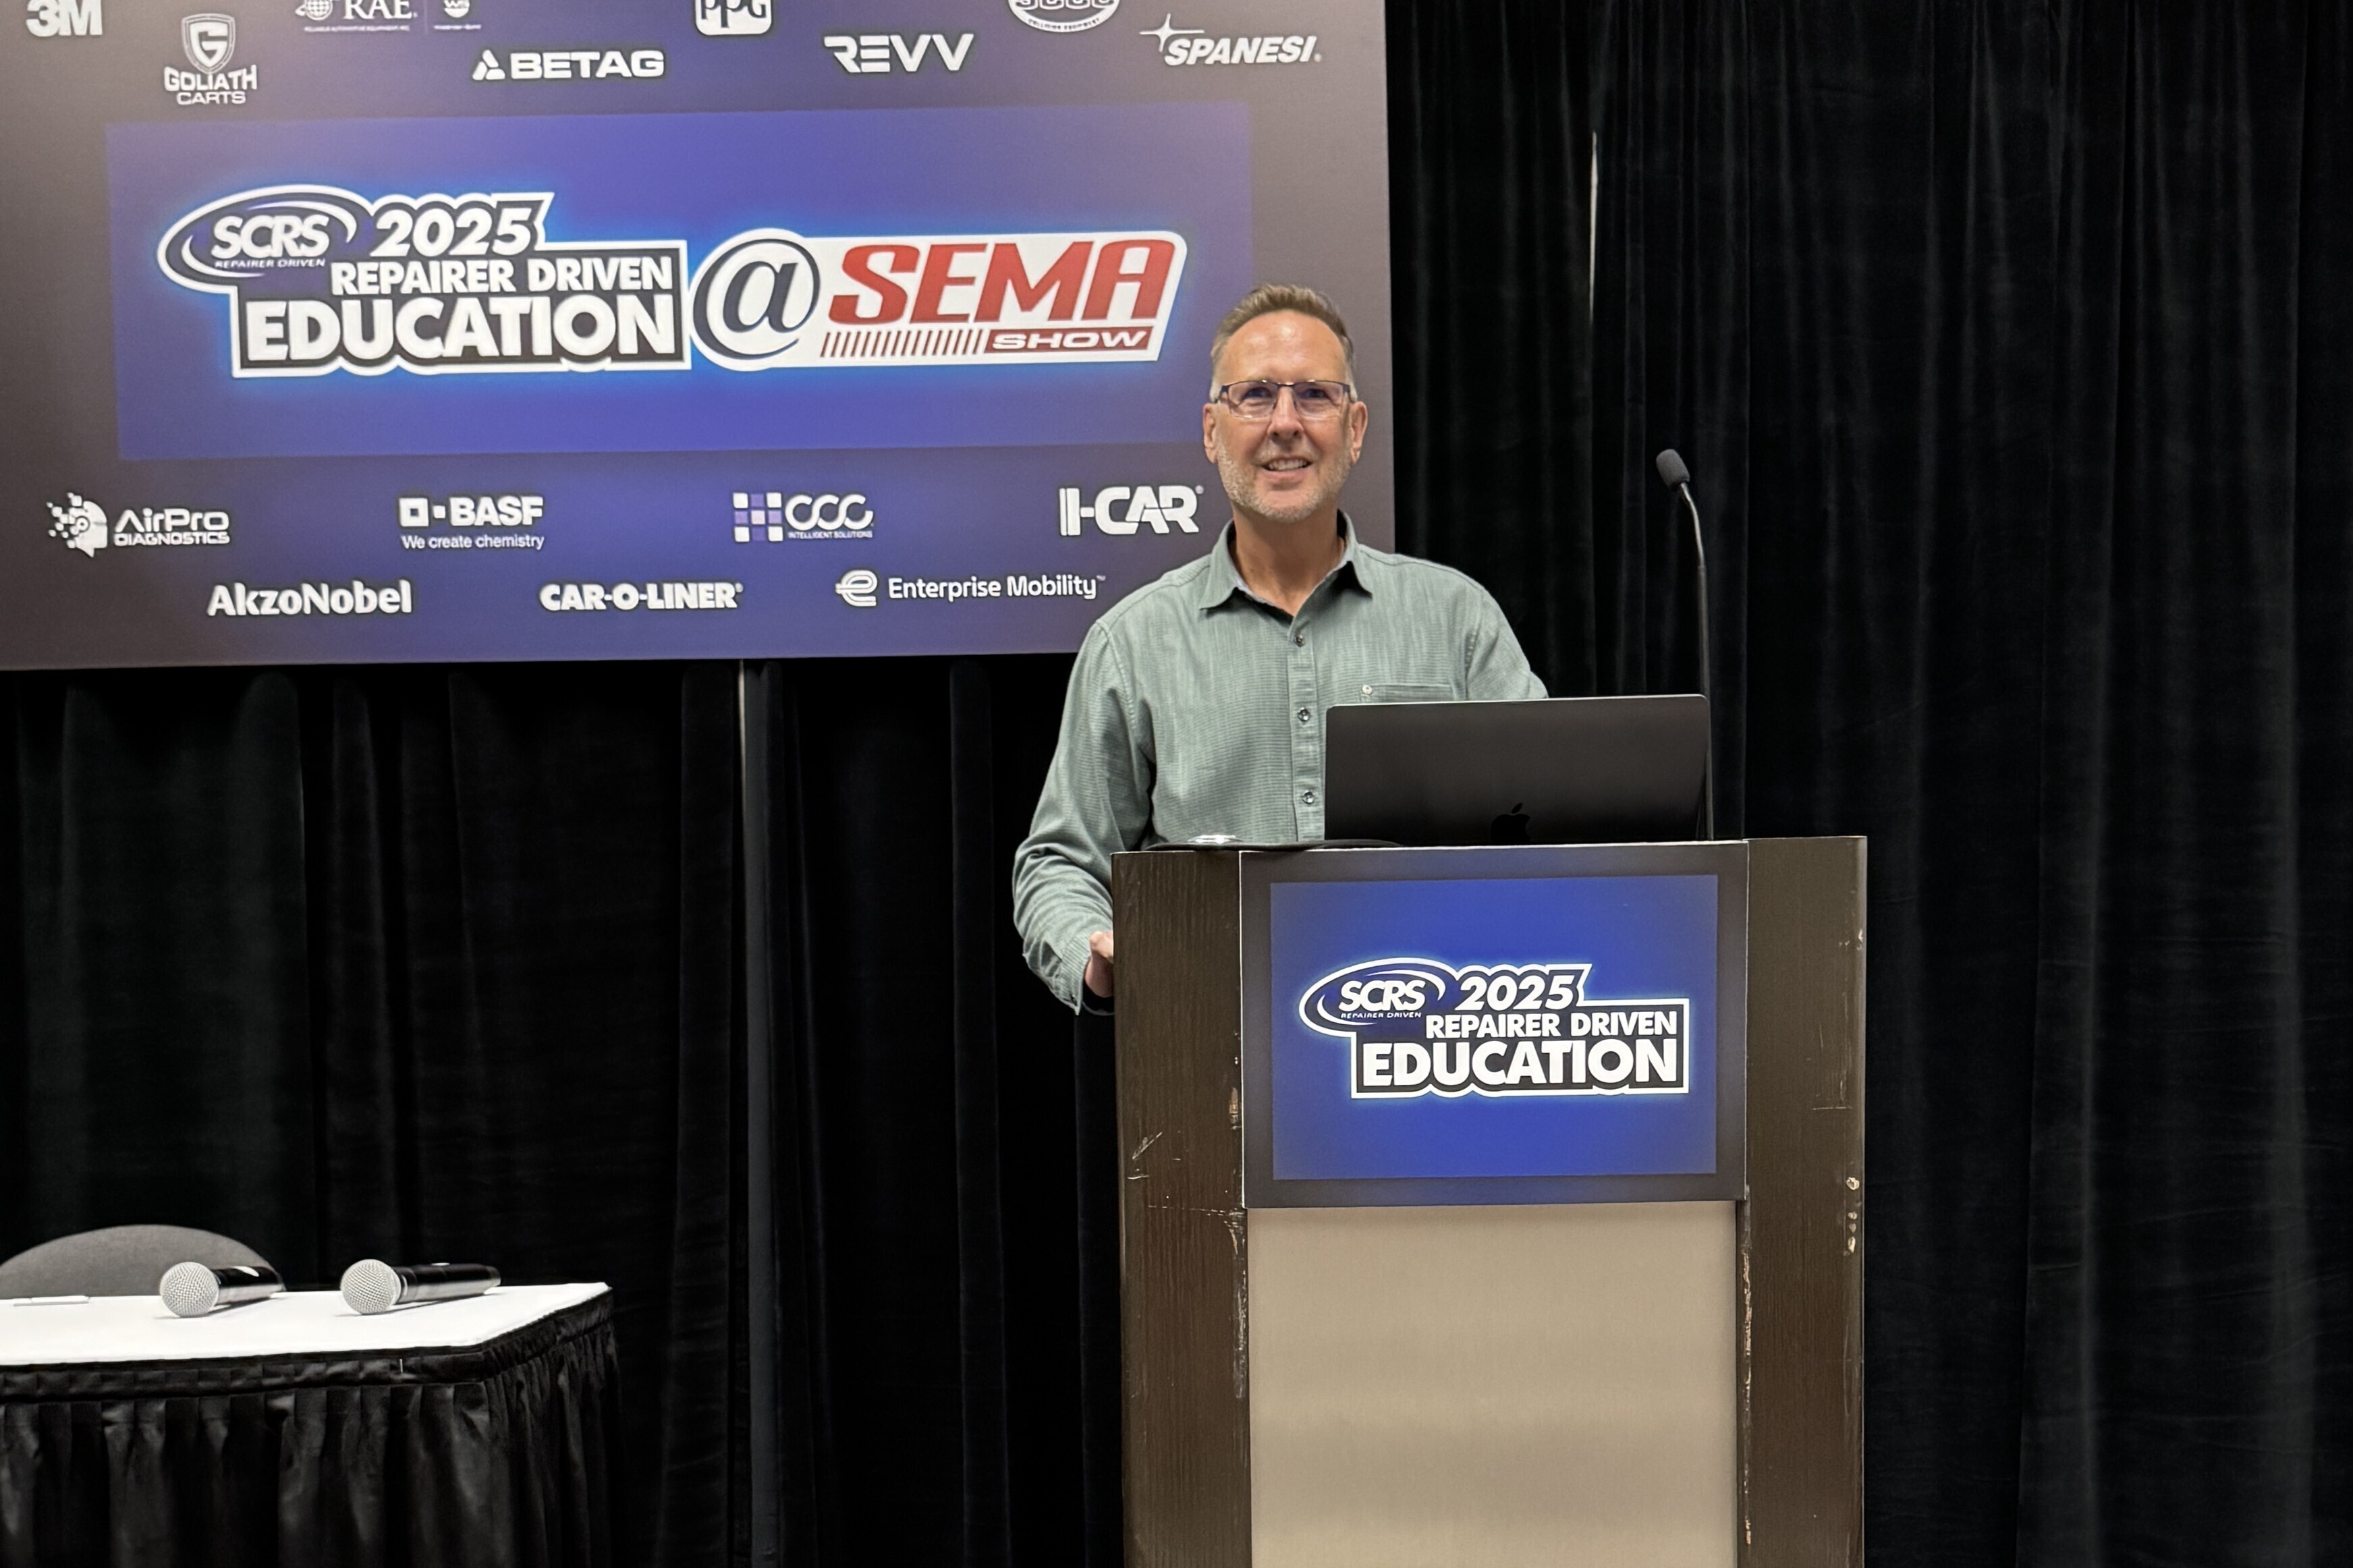
Creating perfect financials, tax optimization, and budgetary planning are all part of building generational wealth, according to Bill Park, owner of Crunchit Financial Services. During the November SEMA Show in Las Vegas, NV, Park gave a presentation titled “The Road to Your Financial Moat” as part of the Society of Collision Repair Specialists (SCRS) Repairer Driven Education (RDE) series.
Park asked attendees if they’ve ever been amazed when a damaged vehicle is dropped off at the shop, and the next day it’s ready to go home. “You wonder, how did that happen?” he said. “We did it that fast because we had structure and it worked … Imagine trying to fix the car without a repair plan.”
Park noted how structure matters when creating long-term wealth. He challenged shop owners to implement structure in their businesses and start with the end in mind.
“Entity structure is everything,” he emphasized. “Don’t overcomplicate it. Make sure your entity structure is clean and tidy and reflects where you are today and where you want to go.”
He described shop owners as “architects” of their business, including the customer experience, treatment of employees, and quality of repairs.
Park said team members make the difference in a company’s success.
“The ‘who’ is everything,” he said. “If you don’t know who in your business is doing everything, who is going to do it? It’s going to fall back to ... you. That’s a bad thing.”
The body shop business trifecta
During any business situation, Park said it’s critical to understand the rules of the game. In this case, he was referring to the IRS’s rules.
He encouraged shop owners to design a 10-year plan using what he called the “body shop business trifecta” to create focus and discipline. It is based on a concept from Mark J. Kohler, a CPA, attorney, and bestselling author. After attending Kohler’s tax and legal tax advisory training program, Park became a certified tax advisor and now runs his business rooted in aspects of the trifecta.
The first two parts of the trifecta include the “money machine,” which represents ordinary income (assets), and investment income (wealth creation). “You want to create your money machine that’s spilling over into your assets for long-term wealth,” he said.
The third part of the trifecta is a revocable living trust, which he highly encouraged shop owners to set up. “The revocable living trust puts you in control of your assets while you’re alive and, more importantly, when you’re dead,” he said.
Otherwise, he said the estate will likely go to probate. “That’s something you do not want to happen.” Not only does a revocable trust prevent probate, but it also allows the business owner to control how the assets are treated and who will benefit.
“You are in 100% control in the event that something bad happens; your kids or other family members aren’t burdened,” he noted. “They can actually carry out your wishes."
LLC vs. S corp
Park talked about the difference between a limited liability company (LLC), which is a business structure, and an S corporation (S corp), which is a tax classification that can be elected by an LLC and provides tax advantages.
He reminded attendees he is not a CPA or an attorney and is not giving advice, but that he has found it beneficial to set up an S corp, which allows businesses to pass corporate income, losses, deductions, and credits to their shareholders for federal tax purposes. Shareholders of S corps report the flow-through of income and losses on their personal tax returns and are assessed tax at their individual income tax rates. This allows S corps to avoid double taxation on corporate income.
“As an S corp flow-through entity, you’re getting taxed on all your profits whether you take the money or not,” he explained. “The more salary you take, the more likely you’re paying."
To ensure the business’s liability protection isn’t at risk, Park said the company must adhere to corporate formalities, including adopting bylaws, holding regular director and shareholder meetings, and keeping minutes.
“Keeping your corporate house in order is deeply important,” Park said. “There are services out there that can do that pretty reasonably, so you don’t have to have it all figured out yourself.”
Setting up a family management company
Under an S corp, business owners can create a family management company and pay their children to work for the business, Park clarified.
“It’s a legitimate expense for legitimate work being performed, and the money can fully fund a Roth IRA account every year,” he said.
Park noted kids under 18 can earn up to $15,750 in 2025 without paying taxes.
“As business owners building our money machine, the goal is to move cash into assets and tax-deferred environments,” he said.
IRA vs. Roth IRA
A traditional IRA allows tax-deductible contributions and withdrawals taxed in retirement, whereas a Roth IRA uses after-tax dollars, so contributions are not tax-deductible and qualified withdrawals are tax-free in retirement. Both have the same contribution limits — $7,000 in 2025, with a $1,000 catch-up contribution for those over 50, according to Park.
He encouraged attendees to consult with a tax advisor to determine the best plan.
Health savings accounts
As part of a company’s medical plan, Park shared the advantages of maxing out a health savings account (HSA). Funds can be contributed pre-tax, grow tax-free, and be withdrawn tax-free for medical costs. The unused money rolls over every year. Those who are 65 can use the funds for nonmedical purposes penalty-free, similar to a 401(k).
“It’s a top-line tax deduction, which is super tax-deferred,” he said. This year, married couples with a family high-deductible health plan (HDHP), for example, can contribute a combined maximum of $8,550 to their HSAs. There is a catch-up contribution of $1,000 per spouse who is 55 or older and not on Medicare.
In addition to receiving a tax deduction, the money can be combined with a Roth IRA and invested, allowing it to grow tax-deferred.
Power of self-directing Roth IRA
“A self-directed Roth IRA gives you control most shop owners don’t even know they’re allowed to have,” Park said. “Instead of being handcuffed to Wall Street, you can invest in real assets you understand, such as real estate, private lending, stock market, or private companies.”
He noted the growth inside a Roth IRA is tax-free. “That means every dollar your investments earn compounds without tax drag and comes out tax-free in retirement. For collision shop owners, this is how you turn active business income into long-term, tax-free wealth that supports your 10-year plan,” he said.
Building perfect financials
After building the body shop business trifecta and 10-year plan, the next step is to create the money machine, Park said. This involves perfect business financials, tax optimization, and wealth planning.
“Perfect financials are financial statements that provide a complete and accurate reflection of your business transactions,” Park said. “Every entry is correctly allocated within the chart of accounts, ensuring 100% accuracy.”
With perfect financials, he said, you can fully trust the data and use it as a reliable benchmark to measure and improve performance.
“Perfect financials do not mean the business itself is performing well — they mean you have the clarity and accuracy needed to see exactly how it is performing.”
Otherwise, the business owner won’t know what to change. “Don’t feel afraid to change if you need to change,” he said. “You have to understand how money flows into your business.”
The three steps to mastering perfect financials, according to Park, are setting up and configuring the management system, maintaining the QuickBooks Chart of Accounts (COA), and creating daily habits to drive accuracy.
“Structure is nonnegotiable,” Park stressed. “If a management system isn’t configured correctly, the COA isn’t mapped to the way a collision shop earns and spends money, and daily habits aren’t tight, the shop is building on a crooked foundation.”
Step 1: System configuration
If the estimating system isn’t set up correctly, Park said the financials will never be right. “What your team codes, how they code it, and how estimates flow determines 90% of downstream accuracy,” he explained.
This step includes reviewing employees’ roles and determining their responsibilities. Park suggested writing code tables that can be used when writing estimates and deciding what should be tracked, such as parts, receipts, and labor categories.
“Set up your people for success,” he urged. “If they’re writing an estimate for an insurer that you have a dispute with, put all those agreements in there to keep you compliant and reduce the number of change requests you get.”
Step 2: QuickBooks Chart of Accounts (COA)
Park advised businesses to take the time to determine if the chart of accounts (COA) reflects what should be measured. “The benefit of a detailed COA is revenue, cost of goods sold (COGS), and expenses.”
A generic COA hides your truth, he said, while a collision-specific COA reveals it. “When labor, parts, materials, supplements, discounts, and sublets are broken out correctly, you finally see where your profits leak and where they grow.”
He encouraged attendees to set up categories that reflect how money is earned and to understand the balance sheet and profit and loss (P&L) statement.
“Every single month you need to reconcile your balance sheet,” he said. This includes verifying that every line item is accurate, that year-end adjusting entries have been made, and that the last asset review has been completed.
The balance sheet is the first document the bank will look at when growing a business to determine how cash flow is managed, he said, noting the importance of being open to modifying the balance sheet and P&L statement to reflect changes in the business.
“The key is knowing how to add that general ledger account and then map it into your passcode tables and those transaction-level activities so that it flows over properly,” he said.
Park also advised conducting a prior period cleanup to make sure transactions are matched and tied back to the management system.
To improve the business’s financial health, Park recommended evaluating the monthly report to ensure it reflects what is being measured and that the financials enable adaptability.
Step 3: Daily habits
Creating daily habits, according to Park, drives accuracy in the business’s financial system.
He suggested exporting to QuickBooks daily rather than batching, which is when multiple closed jobs are stacked.
“Batching can really cause problems because if there is a problem … What’s the likelihood of you remembering it?” he said.
Instead, he stressed the importance of creating a process to export, close, and post all invoices, credit memos, and bank deposits every day, and then attach them to a QuickBooks transaction for audit validation. He also encouraged shop owners to clean and match the bank feed to QuickBooks daily. Maintaining a list of unresolved items can also be helpful.
He recommended auditing the final bills and allocations for the COA to ensure accuracy.
“If you find an error, find out who is responsible and train them,” he said.
Twice a week, follow up on parts credits and return status, review accounts receivable, and make sure everything reflects what’s owed, he said.
“Reconcile everything. It should be zero,” he added. “You either collected it, or you didn’t collect it. Post it and clean it to zero every single week.”
Park said daily habits, including exports, matching, bank feed cleanup, and error correction, create perfect financials and become the scoreboard to trust. Without them, he said, the monthly P&L is fiction and decisions are guesses.
Tax optimization and wealth planning
Park noted that effective capital allocation is critical for tax optimization and wealth planning.
“You really need to look at it as creating a new role for yourself as a capital allocator — the person responsible for allocating resources and capital, money, and people properly.”
A capital allocator understands a business’s debt, profits, distributions, tax-deferred investments, and capital expenses. “Always ask yourself, ‘Do I need it? What’s it going to do for me?’” advised Park. “If your financials are clean, you should be able to do that math in your head pretty quickly, or you should be able to call somebody for assistance.”
Overall, Park said that family is what matters most. “Build that family moat with your kids and parents, and include everybody in your business,” he recommended. “It’s super rewarding."
He referred to the trust as a generational governance vehicle. “That’s the place where you can create your family bank,” he said.
Capital is ultimately the fuel of freedom driven by financial accuracy.
“Decision-making becomes easier because the financial guesswork has been eliminated,” Park acknowledged.
Benefits include paying fewer or no taxes, protecting family wealth, and focusing on the health of the business.
“This is how shops evolve from operators into architects, how families build moats, and you create a business that can run without you — not because you stepped away but because you built it right,” he said.










Stacey Phillips Ronak